blog
I Now Need to Take an RMD — How Does It Affect My Social Security or Pension Income?
Reaching the age when Required Minimum Distributions (RMDs) begin is an important retirement milestone. For many retirees, the first question is not simply, “How much do I have to withdraw?” but rather, “How will this additional income affect my Social Security, pension, and taxes?” The good news is that an RMD generally does not reduce the amount of Social Security or pension benefits you receive. However, an RMD can increase your taxable income and may cause a larger portion of your Social Security benefits to become taxable. Understanding how these sources of retirement income interact can help you avoid surprises at tax time. What Is an RMD? A Required Minimum Distribution is the minimum amount you generally must withdraw each year from certain tax-deferred retirement accounts, including traditional IRAs, SEP IRAs, SIMPLE IRAs, and many employer-sponsored retirement plans. Under current rules, most individuals generally begin RMDs at age 73. The first RMD is for the year you reach age 73, although you generally have until April 1 of the following year to take that first distribution. After that, annual RMDs are generally due by December 31. RMDs are generally taxable as ordinary income unless the distribution includes amounts that are not taxable, such as certain previously taxed basis. Will My RMD Reduce My Social Security Check? Generally, no. An RMD does not reduce your Social Security retirement benefit simply because you took money from your IRA or other retirement account. The Social Security Administration explains that pension payments, annuities, and interest or dividends from savings and investments are not considered earnings for purposes of determining Social Security benefits. IRA withdrawals likewise do not reduce your Social Security retirement benefit. However, there is an important distinction: Your RMD generally will not reduce your Social Security benefit, but it may cause more of your Social Security benefit to be subject to federal income tax. That distinction is extremely important for retirees. How Can an RMD Affect the Taxation of Social Security? The IRS uses a special calculation to determine whether part of your Social Security benefits are taxable. For this calculation, your “combined income” generally includes: Adjusted Gross Income (AGI)+ Tax-exempt interest+ One-half of your Social Security benefits The current base amounts are generally: $25,000 for single filers $32,000 for married couples filing jointly $0 for married individuals filing separately who lived with their spouse at any time during the year Depending on your income, up to 85% of your Social Security benefits may be taxable for federal income tax purposes. An RMD increases your income and therefore can affect this calculation. Example: RMD and Social Security Suppose Mary is retired and receives: Social Security: $30,000 Pension: $20,000 RMD: $25,000 Other taxable income: $5,000 The $25,000 RMD does not cause Social Security to stop or reduce Mary’s monthly benefit. However, the RMD increases Mary’s income. As a result, more of her Social Security benefits may become taxable. This is why retirees should think about their overall tax picture, rather than looking at their RMD in isolation. What About Pension Income? Your pension and RMD are generally separate sources of retirement income. An RMD generally does not reduce a private pension payment. If your pension provides a monthly benefit of $2,000, for example, taking an RMD does not normally cause the pension company to reduce that payment. However, pension income is generally included in the tax calculation to the extent it is taxable. The IRS notes that pension and annuity payments may …
Read MoreTop 4 Tips for Extension Filers
Extension filers don’t have to wait until Oct. 15, 2026, to file their federal tax return. Taxpayers are encouraged not to wait and to take steps to help them prepare an accurate return. Let’s go over a few tips to make completing the return quick and easy. Gather and review tax documents: Complete and accurate…
Read MoreWhy a Payroll Service Is Important for New and Existing Businesses
Running a business comes with countless responsibilities, and payroll is one task that should never be overlooked. Whether you are launching a new company or managing an established business, paying employees accurately and on time is essential. A professional payroll service can help simplify the process, reduce errors, and give business owners more time to…
Read MoreIRS simplifies penalty relief by introducing automatic process
A new automatic process provides penalty relief for clients with a history of filing and paying on time reduces the need for tax professionals to request penalty abatement. The new Automatic Exemption from Penalty (AEP) will replace the long-standing First Time Abate administrative relief. AEP is a systemic administrative relief program expected to begin this…
Read MoreIdentity Protection PINs help taxpayers guard against tax-related identity theft
One of the best ways taxpayers can protect themselves from identity theft is by requesting an Identity Protection Personal Identification Number. What taxpayers should know about an IP PIN · Anyone with a Social Security number or an Individual Taxpayer Identification Number can request a free IP PIN, including taxpayers living abroad. · It’s a…
Read MoreUnderstanding Fringe Benefits vs. Guaranteed Payments for Partners
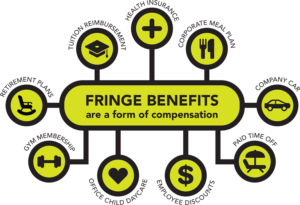
For partners in a partnership, LLC taxed as a partnership, or similar pass-through business, compensation and benefits can be more complicated than they appear. Two concepts that are often confused are fringe benefits and guaranteed payments. Although both can provide economic benefits to a partner, they are treated differently for tax purposes and serve different purposes within the…
Read MoreUnderstanding Required Minimum Distributions (RMDs): What You Need to Know and When to Take Them
As you approach retirement, understanding the rules surrounding Required Minimum Distributions (RMDs) is an important part of retirement and tax planning. RMDs are the minimum amounts that the IRS generally requires you to withdraw each year from certain retirement accounts once you reach the applicable age. Failing to take an RMD on time can result in a significant tax penalty, while taking…
Read MoreWhy Updating Your Form W-4 Can Help You Avoid a Tax Surprise
At Aim Financial, we encourage our tax clients to review their federal income tax withholding whenever their financial or employment situation changes. One of the simplest ways to improve the accuracy of your tax withholding is to complete an updated Form W-4, Employee’s Withholding Certificate. A properly completed W-4 helps your employer determine how much…
Read MoreUnderstanding the Net Investment Income Tax (NIIT)
When preparing your federal income tax return, it’s important to understand that some taxpayers may be subject to an additional tax known as the Net Investment Income Tax (NIIT). Although it doesn’t apply to everyone, individuals with higher levels of income and investment earnings should understand how this tax works and whether it may affect…
Read MoreWhat the “One Big Beautiful Bill” Could Mean for Your Taxes
Tax laws are constantly changing, and keeping up with new legislation can be overwhelming. One of the most talked-about pieces of recent tax legislation is the One Big Beautiful Bill. While headlines often focus on politics, what matters most to taxpayers is understanding how changes in the law may affect their tax return, deductions, credits,…
Read More